Tuesday, August 7, 2018

India’s Big Bank Heist


A record fraud prompts more insistent calls for improvements in an industry grappling with ongoing loan problems.

This article was first published by Global Association of Risk Professionals, Risk Intelligence, on August 03, 2018. Co-author: Anisha Sircar; https://www.garp.org/#!/risk-intelligence/culture-governance/conduct-ethics/a1Z1W000004AsL3UAK

In an article last year, India Confronts Its Non-Performing-Asset Crisis, we wrote about the rise of NPAs in India and how banks and the government had been managing the concomitant stress on its crisis-ridden banking sector. 

Failure to take decisive action regarding mounting NPAs was seen as perilous for the overall economy. Stronger auditing systems and punitive measures have been proving increasingly necessary to curb the festering of bad loans and wilful defaults across the country's public and private banks.

Since 2017, a lot has happened. Nirav Modi and Mehul Choksi have emerged as poster boys for credit-related fraud involving Punjab National Bank, Axis Bank, and Allahabad Bank, with implications for the general stability of the banking system.

Here, we deconstruct the mechanisms that enabled these crimes to occur and look at lessons that can be gleaned from what has been billed as the biggest fraud in the history of India’s banking sector.

The Fraud Is Revealed

In March 2018, Finance Minister Arun Jaitley told Parliament that 1,213 fraudulent letters of undertakings (LoUs, which are letters from one bank to another assuring that a loan will come through by a specified date) had been issued on behalf of companies belonging to Nirav Modi and Mehul Choksi over the previous seven years. 

As it turned out, Modi had acquired these LoUs with the involvement of two employees from Punjab National Bank (PNB) and conducted fraudulent transactions worth Rs. 114 billion, according to initial reports.

Basically, a number of partnerships owned by Modi and Choksi – Diamonds R Us, Solar Exports, and Stellar Diamonds – approached PNB with requests for buyer's credit, to make payments to overseas suppliers.

PNB's letter to the National Stock Exchange and Bombay Stock Exchange, informing them about the fraud a day after it came to light, stated, "Based on these [fraudulent] transactions, other banks appear to have advanced money to . . . customers abroad.”
In other words, based on fraudulent guarantees, banks in India were requested to advance funds to international clients and suppliers through unapproved sanctions issued by certain employees at PNB.

While shares of other banks such as Union Bank of India and Allahabad Bank fell immediately after the fraud was revealed, PNB suffered the most, having lost at least 10% of its market capitalization immediately following the news. Most public-sector bank stocks have been in free fall since February, but PNB has witnessed the largest decline.

bombay stock exchange

(Prices in Rupees)
Source: Bombay Stock Exchange

As shown in the graph, PNB’s shares fell by about 55%, from a closing price of Rs. 171.25 in January when the fraud was revealed, to Rs. 78.7 in July. The scam, a reported swindle of Rs. 143 billion at a time when public-sector banks were already ailing, began highlighted an immediate need to implement more effective practices in the Indian banking system.

How Did They Get Away with It?
Firstly, staff at PNB were hand-in-glove with Nirav Modi. PNB employees.

Gokulnath Shetty and Manoj Kharat approved loans for Modi’s companies to buy and import diamonds for little or no collateral over a reported seven-year period. The fraud came to light when representatives from diamond-importing companies owned by Modi came to PNB’s Brady House branch in Mumbai to ask for LoUs and insisted that they had secured LoUs previously without providing collateral.


Ordinarily, when one of Modi’s companies was borrowing U.S. dollars to fund American diamond purchases, PNB would send a letter in the name of one of Modi’s import companies to the New York branch of another Indian bank, from which Modi was borrowing the dollars. The second bank would then deposit the money into PNB’s nostro account in a U.S. institution, and PNB would release the money to Modi’s company. PNB would repay the lending bank with interest in dollars, while Modi’s company would repay the amount to PNB in India.

But, on the day in mid-January when Modi’s companies applied for new LoUs, the official in charge asked for collateral, and Modi’s executives demurred, stating that they had acquired many letters in the past without being asked to provide collateral. 

When bank officials proceeded to check their database and SWIFT (Society for Worldwide Interbank Financial Telecommunication) records, they found that unapproved LoUs for little or no collateral had indeed been issued to Modi’s and Choksi’s companies since 2011. As the probe deepened, it found that newer LoUs had been requested to pay debts incurred by earlier ones.

Because the bank’s database hadn’t been updated, and SWIFT messages weren’t integrated with customer records, the transfers hadn’t triggered any warnings, and the two diamantaires were able to get away with it for so long. This was the primary vulnerability that invited the attack. The slope might have continued if Gokulnath Shetty hadn’t retired in 2017.

Secondly, lapses in communication facilitated the fraud.

Concurrent auditors that validate transactions on a daily basis neglected to reveal the fraud, and the funds moving in and out of PNB’s nostro account should have raised a red flag when they didn’t square with the actual amount approved by the bank. Further, PNB stated that it did not receive a crucial directive sent out by the Reserve Bank of India (RBI) in November 2016 asking all commercial banks to strengthen their risk mechanism to avert frauds such as these.

After the scam broke out, the RBI sought a compliance report from all banks, including PNB, which could have prevented the fraud. But PNB denied ever having received it. With stronger control mechanisms monitored by the RBI to ensure security, more effective communication at every level, integration of the SWIFT and CBS (Core Banking Solution), and stronger auditing measures, the fraud could well have been prevented in any bank.

The Continuing NPA Crisis
Non-performing asset and loan frauds, which are cases where borrowers intentionally deceive lending banks by deferring the repayment of loans, continue to be a massive problem. World Bank data reveals that India is among the top 30 countries in the world in terms of non-performing loans to total gross loans. The RBI's statistical tables show that NPAs have been on an upward trend since 2012.

reserve bank of india

(Amount in Billion)
Source: Reserve Bank of India

Source: Reserve Bank of India

According to a Reuters report, bad loans surged to a record $149 billion last year. An RBI response to a right-to-information request showed that 8,670 loan fraud cases totaling Rs 612.6 billion occurred over the last five financial years, up to March 31, 2017.

Also, in February this year, the Rs. 36.95 billion Rotomac case involving wilful loan defaulting came to light, as did the mounting loans of Videocon, driving home the urgent need to plug every loophole that has been deepening the dilemma of loan defaulting. These cases expose the magnitude of the problem in a banking sector that is increasingly under the hammer for poor lending practices.

Stronger Regulation

As such, regulators have sought to strengthen measures to have banks fully disclose bad loans, speed up their recovery through recapitalization, and start actively highlighting cases of fraud, without concealing them as cases of NPAs.

Last year, the government said it would inject $32 billion this financial year and the next. In the wake of PNB and Rotomac, the RBI sent out a circular revising its Insolvency and Bankruptcy Code (IBC) and redefining some its “defaulting” taxonomy, stating that a company must be termed a defaulter if it fails to repay a loan within 91 days. 

Despite bankers and companies being unnerved by the new clauses, and lobbying with the center to reconsider, the RBI expressed strong objections to relaxing the new norms.

Regulatory steps such as these seem well-intended and capable of making an impact in the long run. But for real change to occur, the fundamentals need to be addressed. People need to start acting in a more moral manner, for which one might need to face a much stronger penalty. Financial crimes such as these could perhaps be avoided by borrowing from the conceptual predicament of ensuring everybody's skin is in the game.

While the extent of the fraud is unmatched, the case of Nirav Modi is not isolated in India and has been allowed to continue with frequency due to systemic issues such as corruption, poor lending practices, failing monitoring mechanisms, communication lapses, and technological issues.

Apart from regulatory reforms, ultimately, perhaps the only way to ensure that people don't take undue risks is by making sure they have to share in the risk-taking.

With one's personal liability at stake, it would be considerably more difficult to make less responsible choices and challenge the larger interests of society, and thereby arrive at a state of exponentially growing Naturally Performing Assets restoring India's banking sector.

Saturday, August 4, 2018

Of challenges and choices facing working women

This article was first published in Fortune India on August 3, 2018. Co-author: Sai Nitya Bodavala;
https://www.fortuneindia.com/opinion/of-challenges-and-choices-facing-working-women/102241


Women are climbing up the ranks to reach the highest echelons of an organisation, but much more needs to be done if the workplace is to become truly inclusive.


Last year, Nisaba Adi Godrej, daughter of industrialist Adi Godrej, was appointed as executive chairperson of Godrej Consumer Products Ltd; she was 39. The Harvard-educated scion of the Godrej group has played a major role in the meteoric growth in market capitalisation of the company ever since she was inducted into the company in 2000. 

Dhivya Suryadevara, also Harvard-educated, chief financial officer designate of General Motors (GM), is 39 years, too. Her growth at GM has been stupendous.
These women being educated at Harvard and given key roles at their organisations at the age of 39 are just coincidences. Nisa is from a business family, while Dhivya joined GM as a professional.

Both have carved a niche for themselves in the corporate world. On the one hand, we have such role models and on the other, participation of women in the workforce in India is on the decline.

 According to data from the World Bank, the female workforce participation (as a percentage of total workforce in the country) was approximately 28% for India in the nineties. It declined to 24.5% in 2017, while the global average has been around 39% throughout.
Various studies have pointed out that increased participation of women in the workforce will have a significant positive impact on the GDP of nations. Yet the decline, in India, is not really puzzling. At the heart of the matter is the deep-rooted patriarchal society that has defined the central role of women as homemaker.
What is keeping women away?
Literacy rate: Women accounted for a large part of the workforce in agriculture. Over the last few decades, owing to uncertainties associated with agriculture and better opportunities in manufacturing and services sectors, many families have moved away from farming.

However, the women in these families continued to work on farms, as they were not educated enough to find other work. According to data from the last census, in 2011, the literacy rate for women in rural areas was only 59% as against 79% for men; in urban areas it was 80% when compared with 90% for men.
Socio-cultural causes: Despite a history of women contributing on farms in the agrarian Indian society, as the country gradually started to industrialise and urbanise, societal expectations were that a woman’s primary duty involves caregiving and child-rearing.
It was an unspoken rule that she must obtain the approval of her family if she wished to work. It was thought shameful if one’s wife or daughter goes out to earn money instead of staying at home.
Unpaid work: Hiring processes have not been immune to the patriarchal manner of thinking. It is assumed that women have to keep up their primary duties, and therefore are a bad investment. The first part of this assumption is true in most cases making it very difficult for the women to juggle roles.

McKinsey Global Institute estimated that when compared to men, women perform 9.8 times more unpaid work in India (globally it is three times) and if they were to be compensated, it could add an additional $0.3 trillion to India’s economic output.
Lack of infrastructure and sensitive policies: When a woman secures a job, lack of safe transport facilities, and dearth of crèches at workplaces hinder their progress and mobility. Further, corporate policies are largely designed to rule out ambiguity.

In the process they become inflexible. Yet, to attract more women to the workforce, flexible timings and focus on achieving targets would be needed rather than stipulations such as physical presence from 9 to 5.
Pay gap: Gender pay gap is the difference in the average hourly remuneration earned by men and women. According to the World Economic Forum’s 2017 report on the Global Gender Gap, it will take about 217 years for the disparities in employment opportunities and wages, to disappear.

According to the latest Monster Salary Index, the gender pay gap in India across all sectors averaged at 20%. Manufacturing industry has the highest pay gap at 34.9% closely followed by the IT industry at 34%. Financial services and communications sector has the lowest pay gap at 17.70%. Pay gaps are demotivating and fills one with a feeling of being less worthy.
Let the tail become fatter
Considering the massive opportunities in terms of GDP it only seems right to take steps toward the achievement of equality in the workforce. The banking sector has shown promise in this regard. The sector realised the need for gender neutral policies early on. As a result, we have seen many women who have risen up the ranks to reach the highest echelons of an organisation, such as Arundhati Bhattacharya, former Chairman of the State Bank of India, and Kalpana Morparia, CEO of JP Morgan India.
Similarly, many family businesses have been encouraging women from the next generation to play active roles in the business. The involvement of women in boardrooms and in senior leadership positions has increased the focus on issues faced by women in organisations.

Many of the next generation women leading family businesses are making their firms sensitive to the needs of women employees.
Dhivya and Nisa seem like outliers. It can be argued that they were fortunate. But the tail is becoming fatter. The mean is shifting to the right. According to McKinsey Global Institute, even if India does not achieve its full potential, under best-in-region-scenario, a further $0.7 trillion could be added to the GDP by 2025.
Non-participation versus inequality
Amartya Sen, Nobel prize winner for Economics, in his book Inequality reexamined advocated the capability approach to measure equality. He showed that equality can be measured in much wider terms such as empowerment, quality of life, choice of living the way they want, and so on, not just in terms of monetary or economic output (as the debate on gender parity is being made out to be).
“The pervasive diversity of human beings intensifies the need to address the diversity of focus in the assessment of equality,” Sen writes in his book. For example, Sindhu Mohan, a post-graduate from a premier management institute in India, chose to retire to a life with kids, friends, travel, books, sports and fun after a few years of slogging it out as a banker.

There is no inequality in play in her case. It is a choice. Hence, not all non-participation in the workforce can be termed as inequality.
What is important is that if a woman wishes to work, and is as capable as a male counterpart, she receive equality in all aspects. In conclusion, capability and not gender should be the deciding criterion for a job.

Finally, the mindset of men needs to change if true gender parity, in terms of capabilities, choices and opportunities is to be achieved. The men need to be ready themselves for an equal society as the women march forward despite the challenges.

Wednesday, June 13, 2018

Is India’s QIP Destroying Investor Wealth?


This article was first published in the Global Association of Risk Professionals on June 01, 2018. Co-authors: Nikhil Rastogi, Chakrapani Chaturvedula
Analysis indicates that an institutional share-issuance program is associated with lower shareholder returns.
Imagine you are an investor in one of India’s listed companies whose share price is Rs.100. You come across an announcement that the company is offering some shares to institutional investors at a price of Rs.95. You wonder why, but then you just let it go. 

As you track the stock price over the next few months, it falls below Rs.100 and even below Rs.95 – even as the broad market is trading at higher levels than at the time or the institutional offering. Maybe the company’s performance was bad, you wonder. But you also observe many such examples of companies trading below their offering price.
Welcome to the world of Qualified Institutional Placement (QIP).
QIP is one of the methods of raising equity by listed companies, with follow-on offer, rights and preferential allotment being the other methods. Under QIP, started in 2006 by the Securities and Exchange Board of India (SEBI) as a faster and cost-effective way to raise capital, shares are issued to a select group of Qualified Institutional Buyers (QIBs) – usually mutual funds, insurance companies, etc. – at not less than the average of the last two weeks’ high and low price (also known as floor price). A further discount of 5% on the floor price was allowed by SEBI in later years.
We reviewed the return performance of 84 QIPs from 2010 to 2016, in terms of average holding period returns for 3 months, 6 months and 1 year post the issue of QIP. Thus, we broadly analyzed whether on average investors made or lost money on QIP investments.
As depicted in the bar chart, average short-term holding period returns (3 and 6 month) are negative for all years. Excepting 2013, 1-year average returns across all years are negative or very marginally positive.

Index Comparison

 QIP finance

Since the returns could be impacted by general direction of the market in a specific year, we also computed comparable, average holding period returns of the S&P BSE 500 index. For each year, we use S&P BSE 500 index price at the same time that a QIP was issued, and then use the index level 3 months, 6 months and 1 year hence to compute the returns. These are then averaged to arrive at returns for a particular period (3-month, 6-month and 1-year).
As depicted in the bar plot, 3- and 6-month returns are positive for most of the years. Except for 2015, the 1-year returns are positive for all years between 2010 and 2016.
This in essence means that QIPs have not been such a good investment for QIBs as compared to returns on an unmanaged index such as S&P BSE 500.
Now, here we are not measuring the performance of lay investors. These are expert investors getting paid to make investment decisions, and on an average they are losing money for all holding periods from 3 months to 1 year, both absolutely and relatively (compared to S&P BSE 500).
Double Whammy
Another point to note is that many of these QIPs have been issued at a discount of around 5% to the trading price (average two weekly high and low price before the QIP offer). From the perspective of long-term, non-QIB investors this comes as a double whammy. First of all, non-QIB investors are not offered shares at discounted prices; and to add insult to injury, the stocks trade below this price for the next year.
The analysis until now shows that, prima facie, both QIB and non-QIB investors are losing money for average holding periods of 3 months, 6 months and 1 year. But could it really be true for QIB investors? As per the QIP regulation, the issued shares have no lock-in period; that is, they can be sold by QIBs at any point after the issue is made.

 This is as opposed to the regulation in a preferential offer (another method of raising equity by listed companies), where there is a minimum lock-in period of 1 year – the shares cannot be sold before one year. So technically, making use of this regulation, smarter QIBs might be selling the shares so issued, thus driving down the prices of stocks.
We do not have access to detailed data of holdings of respective QIBs across different dates, and we cannot infer if QIBs are moving out of the stocks after subscribing to them. However, the results are consistent with the view that on an average QIP, shares are witnessing downward pressure on account of selling, which is leading to negative holding period returns.

This selling pressure is more likely to come from experts (QIBs) rather than others. The source of selling may be a mystery, but to retail investors, the broad message is clear: QIP could be synonymous with dip.

Thursday, May 24, 2018

General Data Protection Regulation: What will happen to all the micro level analytics?


This article was first published in Analytics India Magazine on May 19, 2018; Co-author: Sanjay Fuloria

The recent episode involving Facebook and Cambridge Analytica raised data privacy concerns once again. This resulted in the closure of Cambridge Analytica, once a high-flying consulting company. They, allegedly, stole user data from Facebook to micro analyze the profiles of individuals.

Based on this micro analysis, Cambridge Analytica advised political parties on campaigning in elections. Facebook CEO Mark Zuckerberg also had to face some very tough questions at the Congressional hearing as a fall out of the above episode. On the face of it, data theft notwithstanding, this is a practice quite rampant in today’s digital world. 

Companies have terabytes of data which they analyze to promote their products and services by targeting the right audience, whether the consumer likes it or not.

With this background, the General Data Protection Regulation (GDPR) formulated by the European Union (EU), is coming into full effect from May 25, 2018, with the objective to protect data at the individual/consumer level. According to this regulation, the control of the data resides with the individuals. If they decide not to share their data, companies can’t use that data. Non-compliance or breach would result in huge fines. Some of the important points covered under GDPR are as follows:
  1. There is a penalty of €20 million or 4% of worldwide revenue for non-compliance.
  2. Consumers should opt-in for consent.
  3. GPS locations are also included in the definition of personal data.
Now, considering most of the global companies have huge analytics departments filled with data scientists, many of whom are PhDs, consumer data is their stock in trade. All their algorithms need copious amounts of data to function well. A lot of marketing programs use the individual level data to design marketing campaigns, both online and offline. 

When someone searches for a book online, for example, she gets a list of similar books she could buy. Now, if the individual doesn’t want to share this data with the company, the company will have to delete this information about the individual. 

The individual has a right to be forgotten as per the regulation. If a majority of individuals decide not to share their data, the marketing campaigns and the analytics engines would all go for a toss.

Some other global companies have outsourced their analytics work to niche vendors. They would also face the same data problem. This regulation applies to any company providing services to EU citizens irrespective of whether the company has a physical presence in the EU or not.

The companies will have to find an alternative approach to deal with consumers. They may not have sufficient time though. As far as GDPR compliance goes, only 7% companies are fully compliant as the May 25th deadline approaches.

As per a Crowd Research report, very few companies (only 40%) are hoping to be compliant by the deadline (https://www.zdnet.com/article/gdpr-compliance-for-many-companies-it-might-be-time-to-panic/). This becomes a tricky situation for the companies even before the analytics experts ask for individual data.

If the individuals raise a complaint after the deadline that their data was misused, companies are bound to pay a hefty fine. What about the individual level data that is already stored in company servers and on the cloud? It will take a huge effort and investment on the part of the companies to make that data safe and reach compliance.

This applies to machine learning algorithms as well. The whole premise of machine learning is that new data should be continuously fed to the algorithms to make adjustments and provide better predictions. Autonomous cars, for example, use image processing and they do need human images. 

Imagine a scenario where human beings refuse to share their images. Of course, the data scientists will have images of animals, trees and other objects to feed into their algorithms but this won’t prevent the autonomous vehicles from bumping into human beings leading to dire consequences.

We have already had a case in the U.S. where an autonomous car hit a human being resulting in death.

With the latest voice recognition technology and the advent of devices like Amazon’s Echo and Google’s Home, individuals are supposed to feel more comfortable with less friction in their lives. 

For this to happen, the speaker has to be ‘ON’ all the time and it will record whatever is spoken at home leading to dire consequences. This data will also be stored somewhere on the cloud. Sooner rather than later, individuals would not want their data to be shared between devices, going back to the earlier era of zero connectivity. It is still to be seen how all this plays out.

Companies are concerned that GDPR compliance will make the jobs of their employees more cumbersome and would make it very difficult for them to do business. They are hoping fines won’t be levied so soon after all and the deadlines might get extended. 

Whatever be the situation on May 25th, 2018, data privacy concerns are going to get shriller. Companies need to be ready with a ‘Plan B’, as far as their analytics strategies are concerned.

Tuesday, April 17, 2018

India’s Regulatory Dodgeball with Bitcoin


Government warnings have hardly restrained one of the world’s most active cryptocurrency markets.

This article was first published in the Global Association of Risk Professionals on April 13, 2018. Co-author: Anisha Sircar


One in every 10 bitcoin transactions in the world takes place in India, according to cryptocurrency payment company Pundi X. https://pundix.com/  Indian trading in bitcoin grew substantially in 2017, with over 2,500 people trading daily.
Demonetization of high-denomination Indian currency in November 2016 triggered an explosion of interest in alternative currencies. According to some estimates, the volume of rupee-denominated bitcoin trades is third in the world, behind only U.S. dollars and Japanese yen.
However, on February 1, Finance Minister Arun Jaitley announced – after similar warning statements by the central bank in 2013 and twice in 2017 – that the state does not consider cryptocurrencies legal tender. The already-slumping value of bitcoin plummeted further, by an estimated 6.5%.
Still, cryptocurrency operators remain positive about the future of virtual currency, and some economists are convinced that this evolving technology will determine the future of the global economy.

Not Explicitly Illegal
The Reserve Bank of India has taken a stance against licensing any entity to operate with bitcoin and other virtual currencies, and frequently communicates warnings to users, holders, and traders about the risks that they are exposing themselves to.
On December 29, 2017, the Ministry of Finance issued a statement http://pib.nic.in/newsite/PrintRelease.aspx?relid=174985 emphasizing that virtual currencies had no legal tender in India, equating them to Ponzi schemes, and saying that transactions, because they are encrypted, are “likely being used to carry out illegal/subversive activities, such as terror-funding, smuggling, drug trafficking and other money-laundering acts.”
By not declaring virtual currencies legal, and by choosing not to regulate them without actually declaring them illegal, the government placed bitcoin in a troublingly grey area. (This is in contrast to Japan, Canada, Australia, Estonia and Chile, which have legalized it; and Bolivia, Iceland, Vietnam, Venezuela and others that have either banned it or imposed punitive measures.)
Moreover, at the beginning of 2018, Indian cryptocurrency exchanges and payment gateways received notifications from banks to make immediate changes to the way money flowed into their platforms, and warning them of account closure if they didn’t comply.
Koinex, India’s largest cryptocurrency exchange, posted a statement https://medium.com/koinex-crunch/inr-withdrawals-update-january-7-2018-6279bbe42bd2  on January 7: “A tussle between our payment service partner and their bank has caused an indefinite delay in the settlement of a large portion of deposits to Koinex in the past 2 weeks . .

While we have taken firm action, we are also in constant touch with the payment service provider and are providing our complete cooperation to help resolve the matter at the earliest.”

Vague Authority
The rationale behind Indian banks’ moves to suspend virtual currencies in India remains unclear, but hint at a directive from the central bank, which, as noted earlier, has shared an uneasy relationship with the traction of bitcoin in India. 

This directive would fall in line with the general pattern of task forces, nationwide surveys, and notices to traders and financial intermediaries to rein in what governments and banks believe to be a dangerous emerging phenomenon.
However, despite statements and actions discouraging people from trading and investing in bitcoin, several Indian investors began doubling down on the cryptocurrency market, driving bitcoin prices in the country even higher than global market trends.
The number of registrations across exchanges in India surged; bitcoin prices jumped nearly 14-fold in 2017, hitting an all-time high of $19,500 by mid-December (before plummeting to $12,000 and then recovering to $17,000 early in 2018). Trading volumes began doubling in the first weeks of 2018 (see figure 1).
Figure 1
bitcoin finance
Source: Coin Dance

This general rise in Indian bitcoin trading volume occurred despite the backdrop of a tumultuous global cryptocurrency market. Its popularity in India, particularly among celebrities and entertainers, is due to its appeal primarily as a financial asset, according to Zebpay, India’s first bitcoin exchange, as well as a market for remittances.
The drop in bitcoin trading volumes, from INR 83,214,245 to INR 11,637,525 between January 27 and February 10, seems to owe itself to the budget announcement. on February 1, in which Finance Minister Jaitley stated, “The Government does not consider cryptocurrencies legal tender or coin, and will take all measures to eliminate use of these crypto assets in financing illegitimate activities or as part of the payment system.”
Citi India, the only multinational bank among primary card issuers in India, on February 14 banned its customers from using the bank’s cards in purchasing cryptocurrencies:
 “Given concerns, both globally and locally including from the Reserve Bank of India, cautioning members of the public regarding the potential economic, financial, operational, legal, customer protection and security related risks associated in dealing with bitcoins, cryptocurrencies and virtual currencies, Citi India has decided to not permit usage of its credit and debit cards towards purchase or trading of such bitcoins, cryptocurrencies and virtual currencies.”
At the same time, it was reported https://news.bitcoin.com/more-crypto-jobs-in-india-despite-delhis-stance-on-bitcoin/   that jobs and applicants for employment in the country’s cryptocurrency sector have increased.

Allure Despite Volatility

During one period in 2013, bitcoin’s price increased 85-fold; the following year, it crashed. By the end of 2017, the big U.S. bitcoin exchange Coinbase said that it had signed 12 million customers, surpassing the accounts of several established financial institutions and brokerages, and became the most downloaded iPhone app. https://www.recode.net/2017/12/7/16749536/coinbase-bitcoin-most-downloaded-app-iphone  In early February, talk of government and bank bans caused bitcoin market capitalization to fall 14% in a week. http://fortune.com/2018/02/05/bitcoin-price-crash/ as major international banks stated their plans or actions of banning customers from using their cards to purchase it.

A bitcoin user should invariably tread carefully given the wild price swings.
Bitcoin finance
Source: CoinGecko

Nonetheless, strong interest stoked by geopolitical unease and distrust in traditional financial institutions will perhaps continue to add to the allure of a decentralized, volatile currency outside the control of banks and governments. This has been happening in India amidst flailing international prices, representing an increasing demand in India that supply, particularly with institutional forces working against it, may not be able to handle.
With platforms such as WhatsApp and Telegram making it even easier to connect sellers and buyers of virtual currencies (through the means of the platforms themselves, or through cryptocurrency wallets), the government could be at a loss for ways to stop the spread of cryptocurrency – because if they prohibit exchanges on platforms, the transactions will find a way to migrate elsewhere.
Perhaps the overarching lack of clarity from India’s leadership regarding the legality and mechanics of virtual currencies in India remains a determinant of their survival in the country. 

The larger question for the global economy, however, perhaps extends beyond the regulation of bitcoin – and seems to stem from that of decentralized technology itself, with its power to replace financial transactions, systems of power and meaning, and the very nature of our tomorrow.

Monday, April 16, 2018

ETFs and Liquidity Shocks


Professor Vikas Agarwal on the effects of commonality of stocks under varying market conditions

This interview was first published by the Global Association of Risk Professionals on April 13, 2018

Assets under management in exchange-traded funds have grown from $151 billion in 2003 to more than $3.4 trillion in 2017, according to the Investment Company Institute. 

Like stocks, ETFs trade on exchanges and, like mutual funds, represent portfolios rather than individual companies. But unlike mutual funds, they trade continuously and can track the performance of various indices.

Amid the trend toward passive investing, ETFs offer the advantages of low expense ratios and transaction costs, a high degree of diversification, simplicity and transparency, and tax efficiency.

 Due to the burgeoning size of the market, the impact of ETFs on the underlying stocks is significant. Academic research finds that ETFs increase volatility and reduce liquidity of the underlying securities. In addition, it finds that ETFs increase the co-movement in returns and liquidity of the component securities.

Vikas Agarwal, H. Talmage Dobbs Jr. Chair and Professor of Finance, J. Mack Robinson College of Business, Georgia State University, has been studying commonality in liquidity of underlying stocks owned by ETFs. 

A London Business School (University of London) PhD in finance who has served as a distinguished visiting scholar in the Securities and Exchange Commission’s Division of Economic and Risk Analysis (DERA), Agarwal has published extensively on hedge fund and mutual fund subjects. 

In this interview with Dr. Nupur Pavan Bang of the Indian School of Business, Hyderabad, Agarwal discusses the workings of the ETF market and the findings of his research with Paul Hanouna and Rabih Moussawi of Villanova University and Christof Stahel of the Securities and Exchange Commission (SEC). Agarwal says that the commonality in liquidity affects investors’ ability to diversify liquidity risk, and that it comes at a price.

If ETFs are basically derivatives on underlying securities, when and why does an investor prefer to invest in ETFs rather than index futures?
ETFs provide long and short exposure to many more asset classes, styles, and segments that are not all tracked by futures. Additionally, a typical U.S. large cap long exposure through ETFs can be more efficient than the same exposure by index futures.

For example, ETFs, unlike futures, do not involve a rollover of the expiring contract, which can erode performance for investors with holding horizons spanning beyond the maturity of a futures contract.

According to BlackRock, the annualized rollover cost of a long futures position in large-cap stocks (S&P 500, Euro Stoxx 50, FTSE 100) ranges from 0.9% to 1.4%. The total expense ratio for an ETF on the same indexes can be as low as 0.05% (e.g., the Vanguard S&P 500 ETF). Hence, ETFs provide a more cost-efficient way to track an index, especially for investors with longer or uncertain trading horizons.

Additionally, ETFs provide various exposures to styles (e.g. value/growth, industries), asset classes, and geographies that are not tracked by futures or do not have existing liquid future contracts.

How are ETFs managed, and what are their structural features?
Most ETFs are structured as open-end investment companies and are governed by the same regulations as a mutual fund. Similar to index mutual funds, ETFs have fund managers. 

However, ETFs are fundamentally different from other passive or active funds registered under the Investment Company Act of 1940 since they are traded on a secondary exchange. Unlike closed-end funds, ETF shares can be created or redeemed by ETF primary market makers, called authorized participants (APs).

For U.S. equity ETFs, shares trade concurrently with the underlying basket of securities they hold, thereby providing intraday liquidity to their investors. Additionally, unlike open-end mutual funds, ETFs can be sold short.

The concurrent trading of ETFs and the securities they hold presents the challenge to uphold the law of one price. Therefore, continuously throughout the trading day, ETF prices are kept in line with the intrinsic value of the underlying securities through a process of arbitrage in which APs, market makers, as well as hedge funds and other institutional investors, participate.

How does the arbitrage mechanism work?
APs can engage in arbitrage activity by taking advantage of their ability to create and redeem ETF shares. If ETFs are trading at a premium relative to the net asset value (NAV) of their underlying securities, APs will buy the underlying securities while shorting the ETF in the secondary market until the two values equate. 

At the end of the trading day, the APs then deliver the underlying securities they accumulate during the day to the ETF sponsor in exchange for newly created ETF shares in the primary market. They then use these new shares to cover their ETF short positions.

However, ETF arbitrage is not limited to AP primary market activities, as it also takes place continuously throughout the day by hedge funds and high-frequency traders. Secondary market arbitrageurs hold long-short positions on the ETFs and the main underlying basket constituents until prices converge.

What is commonality, and why should an investor worry about commonality in liquidity?
Commonality represents the co-movement of a stock’s liquidity with the rest of the market. Higher co-movements with systematic liquidity factors imply lower ability for investors to diversify liquidity shocks, which can be crucial in market downturns.

Commonality is especially important in market downturns due to systematic liquidity dry-ups. The higher the commonality of a stock, the more likely it will exhibit liquidity withdrawals in times of market stress.

If ETFs exacerbate the commonality of stocks in their basket, then this would translate in a reduction of the possibility to diversify liquidity shocks that these stocks are exposed to, especially in stressful market conditions, which would give rise to an “ETF-specific” liquidity risk factor.

What should be the benchmark against which we measure liquidity going up or down?
We benchmark the stock to itself by including stock and date fixed effects, and thus exploiting changes in the stock commonality that are related to correlated trading by ETFs due to arbitrage. We also benchmark to other stocks with similar characteristics. In particular, we use two experiments to properly identify the causal aspect of the relation between the ETF ownership and commonality in liquidity.

How does the commonality behave during various time periods (crisis versus normal)?
Our evidence illustrates that ETF-driven commonality is not a crisis-only phenomenon but is also significant in normal times.

What are the implications of commonality in liquidity for investors and policymakers?
Our paper contributes to the policy debate of widespread implications of ETFs in security markets. Specifically, we show that as ETFs continue to grow and gain bigger ownership of stocks, it can reduce the ability of investors to diversify liquidity shocks due to an increase in the commonality in liquidity of stocks included in ETF portfolios.

Friday, April 6, 2018

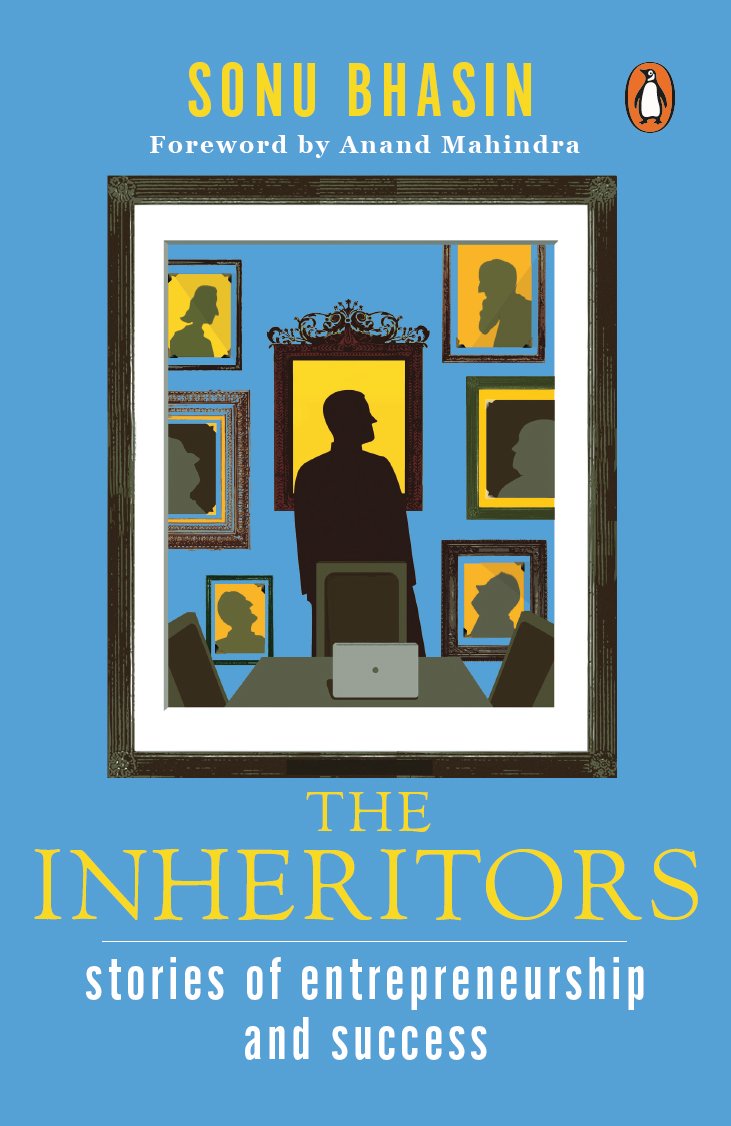
'The Inheritors' book review: Family values seen in entrepreneurship tales


The Inheritors: stories of entrepreneurship and success- Sonu Bhasin


This review was first published in Business Standard on April 06, 2018
inheritors book,family business
Add caption
Penguin Random House India Pvt. Ltd.
7th Floor, Infinity Tower C, DLF Cyber City,
Gurgaon 122 002
First edition (2017)
Rs 299/-

It is easy to feel that the protagonists are sharing their fears and their deepest, heartfelt emotions with readers

Family businesses have been the backbone of the Indian economy since Independence and played a significant role in nation-building even before that.
However, in the era of the Mallyas, Modis and Choksis they have received bad press, a few rotten apples impairing public perception about the rest. Positive stories are hard to come by.

Sonu Bhasin’s The Inheritors fills this gap by narrating the stories of grit, gumption and guts of the next generation of some of India’s well-known family businesses. The exception being Motilal Oswal and Raamdeo Agrawal, who are the founders, not inheritors, of the Motilal Oswal group.

The book is an easy read and the narrative is interesting for the most part, and would engage the layperson as well. The interviews are detailed, insightful and reveal many unknown aspects of the family, the business, successes, failures and strategies. It is easy to feel that the protagonists are sharing their fears and deepest, heartfelt emotions with readers.

Consider the following examples:
Replying to then Hindustan Unilever Chairman Kaki Dadiseth’s overture to Marico to buy out the profitable Parachute brand of hair care products, Harsh Mariwala said, “Mr. Dadiseth, you may think I am a nut but you will find out that I am a tough nut to crack. Thanks, but no thanks”.

Then there is the very human insecurities of a daughter-in-law, now a successful lawyer in her own right, marrying into a prominent family of lawyers. “It was not something that I had ever thought that I would do…I used to look at all the lawyers and my in-laws and feel somewhat intimidated”, said Saloni Shroff who married Rishabh Shroff, the fourth-generation scion of the law firm Amarchand Mangaldas (or Cyril Amarchand Mangaldas as it became after the brothers split in 2015).

Many of the groups and the next-generation leaders whom Ms Bhasin has interviewed for this book are well known and widely covered by the media, so some of the stories may be familiar.

It was refreshing to read about the ones that aren’t as well known- such as Agastya Dalmia of Keventers, a hundred-year-old brand that he revived with two partners, or Arjun Sharma of Select group. Both created new ventures to revive and advance the family business.

The weakness of the book lies in the fact that Ms Bhasin has missed several opportunities that would have given it a longer shelf life. One of them would have been to synthesize the learnings from the leaders’ experiences.

This would have been very helpful for the next generation of the thousands of business families in India. Ms Bhasin also missed the opportunity to weave together a roadmap for the next generation for successfully establishing themselves.

For example, succession challenges plague most family businesses at some point in their life cycle. What was done right in the companies that Ms Bhasin chose for the book?

Another big gap is the lack of an explanation for the choice of companies and leaders featured in the book. Was the choice dictated by convenience, availability or was there a pattern or a logic for selecting the people she did?

To be sure, there are plenty of fascinating stories in the book: The account of Dabur and Amit Burman exemplify professionalisation and separation of ownership from the management; how Pooja Jain found the perfect mentor in her father; why the Dhingras believe that harmony amongst family members is key to the success of the business; how Tara Singh Vachani is proving her mettle through her passion for “senior citizen living”. But why has the writer chosen these groups and not some of the others?

The production also left much to be desired. Pulitzer Prize-winning author Jhumpa Lahiri calls the cover of a book its “clothing”. “If the process of writing is a dream, the book cover represents the awakening,” she writes.

I am not sure if enough thought has gone into designing the cover of the book under review. It is not appealing enough to entice anyone into picking it up at a bookstore. Also, the editing is poor and there are typos. It is to be presumed that these can be taken care of in the future editions and in the digital versions of the book. Lastly, the Foreword by Anand Mahindra could have been longer.

To summarize, the book is well worth a read, not least because with a staggering 90 per cent and more businesses in India being family businesses, success stories need to be told. A little more rigour in the production values and framework may have made it a great book.